Bracing for the Next Hike
September 28, 2026
Global Yields Over The Week
| Yields | Week Ending Sep 18 | Week Ending Sep 25 | Bps Change |
| India 10Y | 7.07% | 7.12% | +5.00 bps |
| India AAA Corporate 10Y | 7.80% | 7.83% | +3.00 bps |
| Bloomberg Asia US Credit Index | 5.83% | 5.97% | +13.50 bps |
| US 10Y | 5.00% | 5.17% | +17.40 bps |
| UK 10Y | 5.28% | 5.35% | +7.00 bps |
| German 10Y | 3.52% | 3.60% | +8.00 bps |
| Japan 10Y | 2.98% | 3.08% | +9.80 bps |
Assets in Review
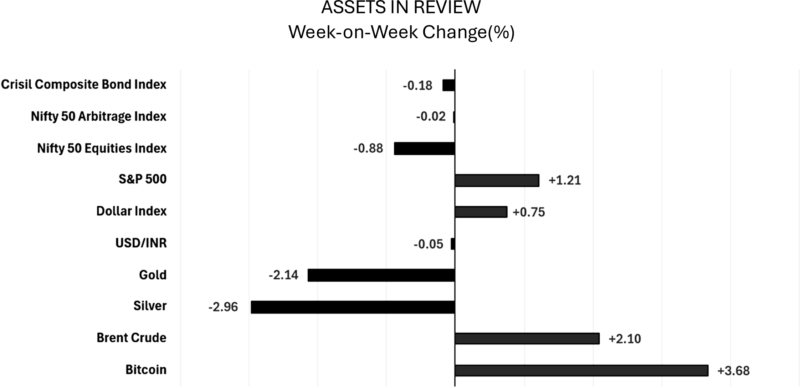
Key Takeaways:
- Global yields rose broadly: US 10Y led at +16bps to 5.16%, followed by Japan (+10bps) and the Bloomberg Asia USD Credit Index (+14bps). India was comparatively muted (10Y +5bps, AAA corporate +3bps).
- US Flash Manufacturing PMI surged to 57.0 (from 53.9) and Services to 58.7 (from 54.6), the fastest business growth in over five years, lifting Fed hike bets.
- Nifty 50 (-0.88%) and Nifty 500 (-1.04%) fell and the Crisil Composite Bond Index slipped 0.18%. The Nifty 50 Arbitrage Index held flat (-0.02%), showing its defensive value.
- DXY rose 0.75% but USD/INR ended marginally lower (-0.05% at 95.82), consistent with RBI’s active FX intervention.
- India’s H2FY27 borrowing is set at Rs.7.86 lakh crore (Rs.16 lakh crore for FY27), with supply shifting toward the long end (15Y share up to 17.6%, 30-50Y up to 28.0%, 10Y down to 26.3%).
- Brent rose 2.10% to $106 on Hormuz uncertainty, while gold (-2.14%) and silver (-2.96%) fell on higher yields and a stronger dollar.
Market Recap
Fixed income saw heavy selling last week after unexpectedly strong US flash PMI data. Business activity grew at its fastest pace in over five years in September and based on the historical relationship between PMI and GDP data, the latest reading points to continued economic growth in Q3. The flash manufacturing PMI climbed to 57.0 (from 53.9), signalling a marked pickup in the sector, while services rose to 58.7 (from 54.6), pointing to strengthening demand there too. This lifted bets on a Fed hike, sending yields to multi-decade highs, the 30Y touched levels last seen in June 2004, and the 10Y its highest since June 2007, with hawkish Fed commentary and elevated oil prices adding further upside.
Indian yields hit a four-month high, tracking the global debt selloff and inflation concerns as Brent held near $105/bbl. With August CPI accelerating to 4.82% and the Fed already hiking, we expect the RBI to follow suit in October. India’s 1Y OIS surged to 6.18%, pricing in 75bps of hikes over the next year. Corporate bonds tracked the move in G-Secs.
System liquidity stayed in surplus but tightened sharply, to 1.55% of NDTL from a peak of 4%, pushing overnight rates back up, partly on excise, advance tax, and GST outflows, and compounded by RBI’s early unwinding of short forward positions, OMO sales, and active FX intervention.
The rupee’s bearish structural trend against the dollar continued, oil-driven, weakening to 95.97/$, while the Nifty was weighed down by soft domestic and global cues.
Macro at glance
India’s central government announced its H2FY27 borrowing program of Rs. 7.86 tn, which is ~49% of the total FY2027 gross borrowing of Rs.16 tn. The maturity-wise composition is broadly balanced, although there is a notable shift within the long end. The 10Y allocation at 26.3% is lower than the 29.0% share in H1FY27, while the 15Y allocation has increased to 17.6% from 14.5%. The share of 30-50Y securities has also risen to 28.0% from 24.9% in H1FY27. The 3QFY27 net short-term borrowing through T-bill has been announced at Rs297 bn (gross issuance: Rs2.99 tn).
Outlook
Focus will remain on geopolitical situation amid Iran’s proposal to a seven-day roadmap to reopen the Strait of Hormuz, and US President Trump’s rejection to the proposal. Any progress towards reopening the key oil shipping route could ease crude prices, while renewed tensions could push them higher.
The local yield curve could steepen briefly given the higher longer end supply as compared to 1HFY27 before flattening again due to likely additional OMO sales and onset of the rate-hiking cycle by the RBI.
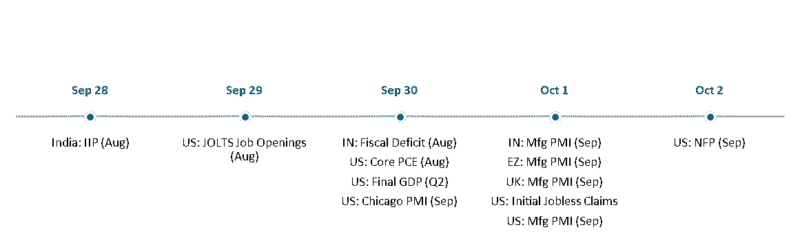
Coming up this week