Inside a Week of Global Rate Hikes
September 21, 2026
HIghlights
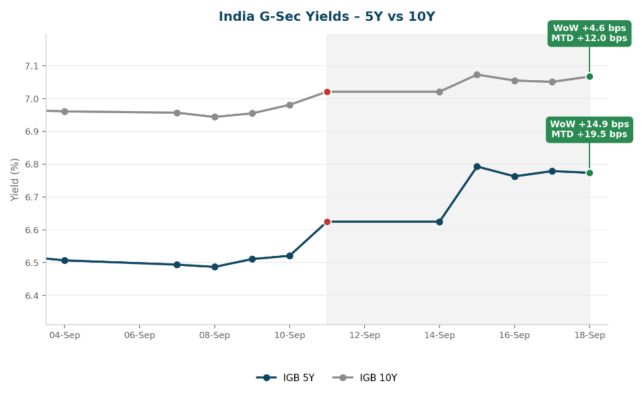
- India’s yield curve experienced a classic bear flattener, the short end rose more than the long end (5Y yield +15bps vs. 10Y yield +5bps), as the Fed’s hike intensified pressure on the RBI to follow suit.
- Rate-hike expectations firmed further, with the 1Y OIS at 6.06% now pricing in an RBI move as soon as October, as markets brace for tighter policy to curb inflation risks from an uneven monsoon and continued crude price volatility.
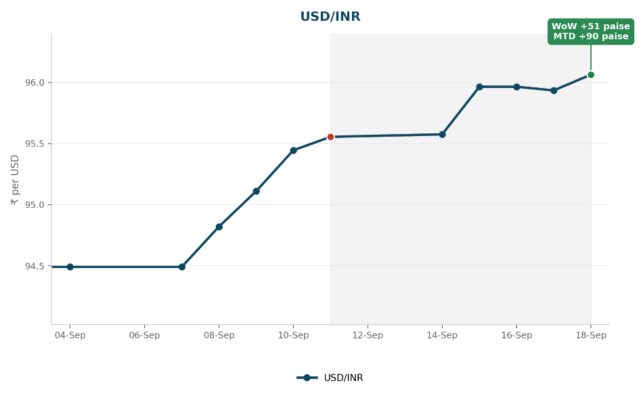
- Rupee depreciated sharply to 96.06/$ (+51 paise WoW), pressured by dollar strength and rising oil.
- AAA corporate spreads widened across the curve (2Y +3bps, 5Y +1bp, 10Y +2bps).
- RBI took active measures to drain system liquidity via OMO sales and VRRR auctions, compounding the natural drawdown from advance tax outflows.
- The Fed delivered its first hike since 2023 (+25bps to 3.75%-4.00%, unanimous), with the dot plot signaling more to come.
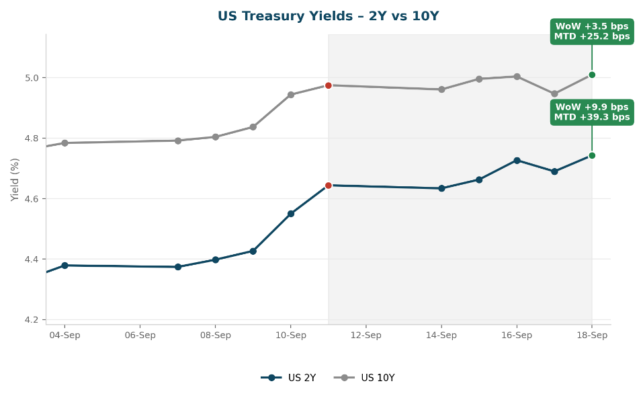
- US 10Y yield touched a fresh high of 5.04% ahead of the decision before easing to 5.01% by Friday, while the 2Y rose 10bps WoW to 4.74%.
- The Bank of Japan hiked 25bps to 1.25%, highest since 1995, yet JGB yields fell and the yen weakened past 157/$.
- The Bank of England held at 3.75%, with a 6-3 split vote after UK CPI accelerated to 3.1%, its first print above 3% since March.
- Commodities stayed volatile through the week, Brent held near $103 for a third straight weekly gain, while gold and silver both clawed back losses after an initial hawkish-hike selloff
India Macro
Markets:
India’s 10Y G-Sec stayed under pressure, breaching 7.07% (+5bps WoW), while the 5Y rose more sharply to 6.77% (+15bps WoW), a short-end-led move driven by rising expectations that the RBI will follow the Fed’s hike with tighter policy of its own (a 25bp move as soon as October is increasingly priced in). Corporate bonds tracked the sovereign move, AAA spreads widened across the curve (2Y +3bps, 5Y +1bp, 10Y +2bps). The 1Y OIS held around 6.06%, suggesting the market has already priced in a cumulative 75bps of hikes.
The rupee bore the brunt of the same dollar-oil dynamic, depreciating sharply to breach 96.1/$ after the Fed’s hike compounded pressure from rising crude prices.
On the liquidity side, system liquidity was drawn down to Rs.6.93 lakh crore through advance tax outflows and deliberate RBI efforts including OMO sales and overnight VRRR auctions, to absorb surplus liquidity that could otherwise blunt monetary transmission ahead of further hikes. The week’s Rs. 50,000 crore OMO sale auction was notable in its own right: it saw a tail at the cut-off, yet RBI still accepted the full notified amount, a signal it prioritized the liquidity drain over price sensitivity, contrary to expectations that demand would fall short.
Focus will remain on the second tranche of the OMO sale auction worth Rs.25,000 crores. An outcome similar to last week could indicate continued strong yield requirements from investors. If the RBI accepts bids for the entire notified amount, continued OMO sales could put further upward pressure on G-sec yields.
Key Releases:
- Reliance Industries priced its return to India’s rupee bond market on 15-Sept at an implied yield of 7.47% (equal to its annual coupon), its first local issuance in nearly three years, raising Rs.12,000cr through AAA (CRISIL)-rated notes maturing in five years.
- India’s BOP surplus rose to $20.8Bln in July vs a $2.9Bln surplus in June, led by an increase in FCNR(B) inflows.
- Forex Reserves fell by $4.9 Bln to $780.8 Bln in the week ending Sep 11 drive by drop in foreign currency assets and gold valuation.
- Deposit growth rose to 17.8% YoY as of 31-Aug (from 16.7%) while credit growth stayed at 19.1% YoY.
Auctions:
- At the weekly gilt auction, the cutoff came in line with expectations for the 7.06% 2041, and the 7.43% 2076 bond.
- The State Development Loans (SDLs) auction across 16 states/securities was comfortably subscribed.
- T-Bills also cleared well: the 91-day at a strong 3.53x cover (yield 5.28%), the 182-day at 4.71x (yield 5.75%), and the 364-day at 4.11x (yield 6.04%).
Global Macro
- Wednesday’s FOMC meeting was the highlight of the week, which delivered a unanimous 25bps hike, lifting the fed funds rate to 3.75%-4.00%, first increase in three years. The dot plot (Fed’s quarterly chart of individual members’ own rate projections) signalled that 16 of 18 officials see at least one more hike this year. Fed chair Warsh described the economy as resilient, however, running with a risk of persistent inflation, envisaging a tighter monetary policy that remains contingent on the upcoming CPI reports and volatility of crude prices.
- US 10Y yield touched 2007 high on Tuesday, inching up to 5.04%, while the 30Y also stayed above 5.30% for most of the week. Right after the hike announcement, the US 2Y yield spiked by 6bps to 4.72%, closing the week at 4.74%. The bond market experienced a brief relief rally post FOMC, as the 10Y yield eased to 4.94% on Thursday. However, the trend remained unsustainable as investors reassessed the long-term landscape, lifting the yield back toward 5.00% on Friday.
- Richmond Fed’s Tom Barkin hits the mic Tuesday and Thursday, and as one of the FOMC’s more moderate voices, his tone could swing rate hike odds heading into the next decision. Most market participants are expecting a cumulative hike of 50-75bps over the next few meetings. The path of yields now hinges on multiple factors, with AI hyperscaler capex also emerging as a potential structural driver of the new baseline level for global debt markets.
- Thursday’s $19bn 10Y TIPS auction tested that backdrop directly, clearing at a real yield (yield above the future US inflation) of 2.653%, the highest in nearly 18 years, and well absorbed despite heavy issuance.
- The Bank of Japan delivered its own 25bps hike, taking the policy rate to 1.25%, highest since 1995. The market reaction was counterintuitive: JGB yields actually fell (the 2Y down 2.5bps to 1.835%, with 5Y and 10Y also easing), while USD/JPY rose above 157. Money market is still pricing ~90bps of cumulative hikes over the next 12 months, with the next move as soon as in December.
- Bank of England held at 3.75% with a 3 out of 9 members pushing for an immediate hike to 4.00% after the CPI accelerated to 3.1% in August, driven by energy costs. The Eurozone told a similar inflation story as the headline CPI rose to 3.2% YoY, even as the core inflation eased to the expected 2.4%.
Commodities
Crude Oil & Natural Gas:
Brent settled the week at $103.87 (-0.9% Friday), still up for a third straight week, as Iran-affiliated strikes forced a temporary halt to Saudi Arabia’s East-West pipeline before alternative routes restoration eased the supply scare.
Precious Metals:
Gold fell sharply on Wednesday’s hike but clawed back the losses by Friday to close at $4,376/oz. Silver outperformed sharply, rising from $63 to $66 (+4.8%) as industrial and investment demand both leaned in.
Coming up this week
|
Date |
Time |
Region |
Event |
Forecast |
|
21-Sept |
5:00pm |
India |
Infrastructure Output (August) |
– |
|
22-Sept |
10:30pm |
US |
FOMC Member Barkin Speaks |
– |
|
23-Sept |
10:30am |
India |
Flash Manufacturing and Services PMI |
– |
|
23-Sept |
1:30pm |
Eurozone |
Flash Composite PMI |
– |
|
23-Sept |
2:00om |
UK |
S&P Flash Composite PMI |
51.4 |
|
23-Sept |
7:15pm |
US |
S&P Flash Composite PMI |
– |
|
23-Sept |
8:00pm |
US |
Crude Oil Inventories |
– |
|
24-Sept |
6:00pm |
US |
Initial Jobless Claims |
201K |
|
25-Sept |
5:00pm |
India |
FX Reserves |
– |
Source: Investing.com