Fed Pauses, Doesn’t Pivot
Oct 29, 2026
The 30-second take
A pause to watch the medicine work, not the end of the course. The Fed held at 3.75–4.00% in a 10–2 vote, with both dissenters wanting a 25bp hike. Markets heard a soft tone and priced a softer dollar, but the December hike is still very much alive. For India, this buys a few weeks of breathing room, not a change in direction: crude and FPI flows still call the tune, and RBI stays in tightening mode.
What actually happened on 28 Oct
The Fed held at 3.75–4.00%, its first pause after September’s 25bp hike. Cleveland’s Hammack dissented for a hike as expected; Governor Cook joining her was the surprise.
The statement upgraded growth from “solid” to “strong”; and framed the hold as time to gather information for a “timely”; return to 2%. In the presser, Warsh called financial conditions tighter but not tight, and the tightening so far “not uncomfortable”. He gave no guidance on December and said politics played no role, six days before the US midterms.
The real surprise was the calendar: rate decisions at only 7 of 8 meetings in 2027 and 6 of 8 in 2028. Markets read the day as mildly dovish. The 2Y Treasury fell about 8bp to around 4.70%, the dollar slipped about 0.2% and equities were flat. The 10Y edged up to about 5.05% on break-evens, and a December hike is still about 85% priced.
Dove in the words, hawk in the math
The tone was soft, but the policy path has not changed. Warsh said little about the recent upside inflation surprise, repeatedly praised how markets were moving, and flagged AI investment as rate-sensitive. Read on its own, that sounds dovish. Set against a strong-growth statement and two hike dissents, it reads more like a Fed buying time than one changing course.
The dovish signals were the missing inflation discussion, a softer dollar, lower front-end yields and fewer policy meetings. The hawkish facts are harder to argue with: two dissents for a hike, growth upgraded to “strong”, Q3 GDP tracking above 3% and inflation still above target. Warsh can easily walk back the soft tone, and the September projections already pointed to one more hike this year.
Way forward: The Fed is in “pause and assess”; mode, not “done”. Expect a 25bp hike on 9 Dec unless October–November inflation cools clearly. The long end stays heavy: 10Y UST near 5% reflects term premium and a ~$2 trillion deficit, not just the policy rate.
What it means for India: Fed helps a little, oil hurts a lot
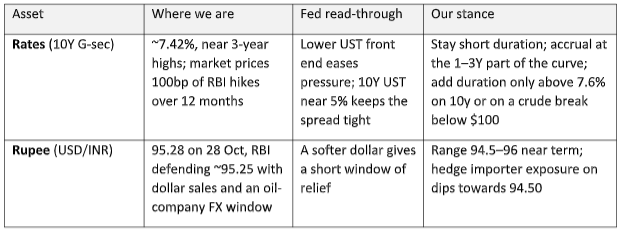
The Fed pause is a mild positive at the margin, but India’s real problem is imported: Brent near $116, CPI at 5.54% in September and record FPI selling. A softer dollar helps; it does not fix those.
So, what does RBI do on 2–4 December?
Base case: another 25bp hike to 5.75%, stance kept at “calibrated tightening”; RBI moved first in October (6–0 vote to 5.50%), and the minutes made clear cuts are off the table. The Fed pause does not change that, because RBI’s trigger is domestic inflation and the rupee, not the Fed.
Three things make the case. CPI is near the 6% upper band, with crude and a weak monsoon feeding food prices.The rupee needs a positive real-rate cushion while FPIs are leaving. And RBI meets a week before the Fed on 9 Dec, so it will likely move pre-emptively rather than wait.
- Hawkish tail (25%): a 50bp move if October CPI breaks 6% or Brent stays above $115.
- Pause (10%): only if crude falls sharply and the rupee holds below 95 on its own.
- Beyond the rate: expect liquidity to stay tight ahead of the festive season, continued FX intervention and more targeted dollar-demand measures for oil importers.
What would change our mind
- Bullish for India: Brent back below $100, a soft US October CPI that takes the December Fed hike off the table, FPI flows turning positive.
- Bearish for India: a fresh Gulf supply shock, 10Y UST above 5.3% again, or rupee breaking 96 despite intervention.
- Dates to watch: US midterms (3 Nov), India October CPI (mid-Nov), RBI MPC (2–4 Dec), FOMC with new projections (8–9 Dec).
Disclaimer: The content of this article is for informational purposes only and should not be considered financial or investment advice. Investments in financial markets are subject to market risks, and past performance is not indicative of future results. Readers are strongly advised to consult a licensed financial expert or advisor for tailored advice before making any investment decisions. The data and information presented in this article may not be accurate, comprehensive, or up-to-date. Readers should not rely solely on the content of this article for any current or future financial reference.