MACRO & DEBT MARKETS WEEKLY
September 16, 2026
HIGHLIGHTS:
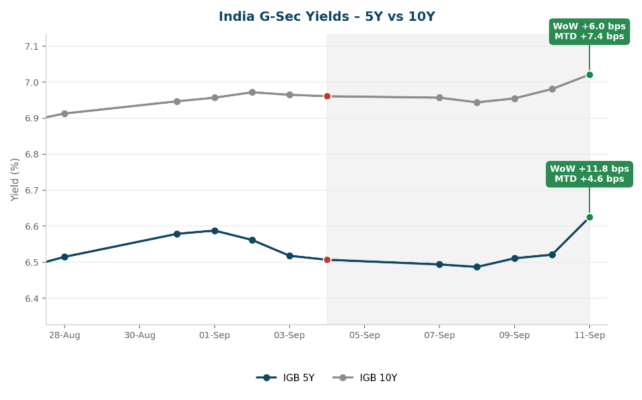
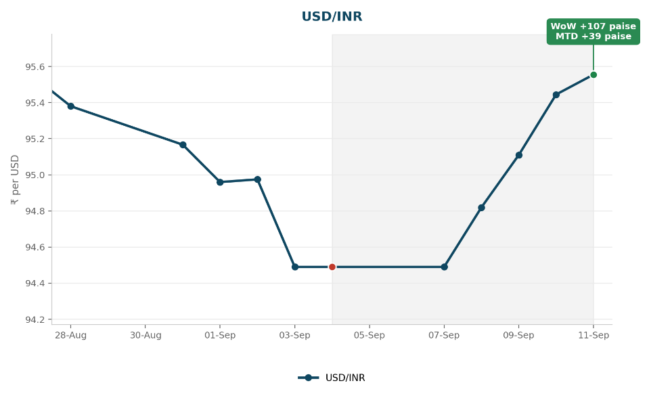
- India’s 10Y G-Sec yield rose to 7.02% (+6bps WoW) and the 5Y jumped to 6.62% (+12bps WoW). Rupee weakened 107 paise against the dollar, breaching lowest level in two months.
- India’s forex reserves jumped a record $44.9bn to a fresh high of $785.7bn.
- RBI announced Open Market Operations (OMO) sales worth Rs.1 lakh crore (across three tranches) to absorb the mounting system liquidity (Rs.10.43 lakh crore).
- Deposit growth accelerated to 16.7% YoY and credit growth to 19.1%.
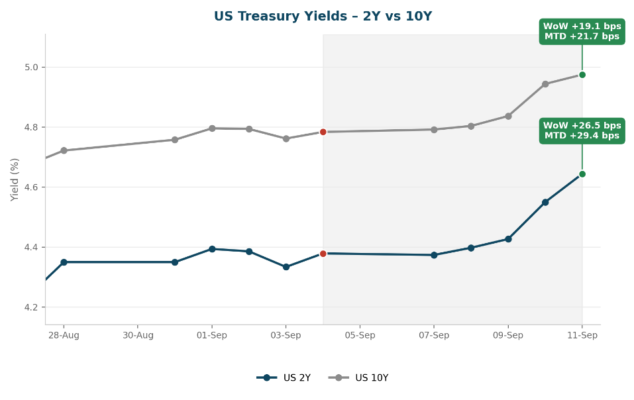
- US yields surged more sharply, the 2Y rose 26.5bps WoW to 4.64%, and the 10Y climbed 19.1bps WoW to 4.98%.
- US CPI for August came in largely in line with expectations, even as a hotter PPI print pushed September Fed hike odds toward 90%.
- The ECB hiked key interest rates by 25bps, citing inflationary pressures, and flagged another hike in October if needed.
- Commodities stayed volatile, Brent spiked to $110/bbl. mid-week on Iran tensions before easing to $104 (still +9% WoW), while gold extended a third straight weekly decline toward $4,350 on surging Fed hike odds.
INDIA MACRO
Markets:
- India’s 10Y G-Sec hardened to 7.02% on Friday (+6bps WoW), while the 5Y rose more sharply to 6.62% (+12 bps WoW). The benchmark remained elevated as oil prices rose amid renewed US-Iran tensions, compounded by RBI Governor Sanjay Malhotra’s comments that the RBI may conduct OMO sales to absorb surplus liquidity.
- Corporate bonds traded mixed, diverging from the G-sec yields. AAA spreads compressed sharply at the short-to-medium end (2Y -14bps, 5Y -11bps), supported by surplus banking system liquidity. The 10Y AAA spread remained unchanged, dominated by duration and inflation considerations.
- The India-US 10Y spread held steady at 205bps WoW.
- The rupee bore the brunt of the geopolitical pressure, depreciating against the dollar to a two-month low of 95.55 against the USD (from 94.49, -1.1% WoW). Equities followed suit, with the Sensex and Nifty both closing the week lower (Sensex -2%).
- System liquidity remained in a large surplus of Rs.10.43 trillion. RBI continued absorbing this through multiple VRRR auctions including a 26-day operation. The lack of response to longer duration VRRR forced RBI to announce OMO sale auction of Rs 1 trillion across three tranches to sterilize liquidity in the market.
- 1Y OIS stayed elevated at 6.10%, indicating a 25bps rate hike by RBI at Oct MPC.
Key Releases:
- Forex reserves jumped by a record $44.903bn to a fresh lifetime high of $785.706bn for the week ended Sep 4, a sharp acceleration from recent weeks.
- Deposit growth rose to 16.7% YoY as of 31-Aug (from 14.7%), while credit growth ticked up to 19.1% YoY (from 18.3%), both pointing to renewed momentum in bank balance sheets.
Auctions:
- The weekly gilt auction saw the 6.20% 2029 paper only partially subscribed, bids of just Rs.45.06bn came in against a Rs.110bn notified amount, triggering a recovery in bond prices.
- The SDL auction across 8 states/securities was comfortably subscribed. T-Bills cleared well across all tenors: 91-day at a strong 4.43x cover (yield 5.21%), 182-day at 3.95x (yield 5.62%), and 364-day at 2.67x (yield 5.92%).
GLOBAL MACRO
- US 10Y yield almost breached 5% before settling at 4.96% (+19bps WoW), and the 30Y held at a 19-year high of 5.36%, driven by escalating US-Iran tensions, crude peaking at $110/bbl., and mounting debt-sustainability concerns. Treasury’s $18.5bn buyback announcement did little to contain the move.
- USD-denominated Asian credit felt the pressure too. The Bloomberg EM Asia USD Credit Index, which tracks USD-denominated government-related and corporate debt across Asia (ex-Japan), fell 0.78% WoW and 0.66% month-to-date, tracking the broader rise in global yields.
- Auction demand in the US was mixed: the 10-year note (9-Sep) cleared at 4.834% with a solid 2.71x cover, while the 30-year bond (10-Sep) saw a softer 2.61x cover and a wider tail (5.308% high vs. 5.250% median yield), reflecting thinner demand and building debt concerns at the long end.
- US PPI for August surged up to 5.4% YoY, pushing September hike odds to 90%. CPI came largely in line (headline +0.4% MoM), though core inflation ran slightly hot at +0.3% (vs. 0.2% consensus). Equities rallied on Friday on the in-line print but still closed the week lower (S&P -0.8%, Dow -1.6%, Nasdaq -0.7%) as oil dominated sentiment.
- ECB hiked the key interest rate by 25bps to 2.65% and flagged another move in October. Germany’s 10Y Bund surged to 3.52% and the UK 10Y gilt held at a multi-decade high of 5.36%. UK’s GDP (Q2) beat expectations with 0.4% growth in July, a print expected to slow as higher energy and borrowing costs increasingly pass through.
- Japan’s JGB 10Y touched 2.98% and South Korea’s 10Y hit a multi-year high of 4.54%. The yen, however, was a standout outperformer among the G10 currencies, fuelled by the US Treasury Secretary’s comments citing ‘asymmetric information’ and openly daring traders to bet against efforts to strengthen the currency, a stance that risks a sharper carry-trade unwind if hedgers continue paring back yen exposure. Japan’s PPI ran hot at 7.6% YoY ahead of an expected BOJ hike. Nikkei and Kospi led regional equity losses (-1.93% and -1.76%).
COMMODITIES:
Crude Oil & Natural Gas:
Brent spiked as high as $110/bbl. mid-week on escalating US-Iran tensions before easing to $104 by Friday, still up nearly 9% for the week. Natural gas moved the opposite way, falling to a three-week low near $2.80/MMBtu on a larger-than-expected storage build.
Precious Metals:
Gold extended a third straight weekly decline toward $4,350/oz as hot PPI data pushed September Fed hike odds to 90%. Silver was hit harder, tumbling over 5% in a session before steadying near $63.5 on the same hawkish repricing.
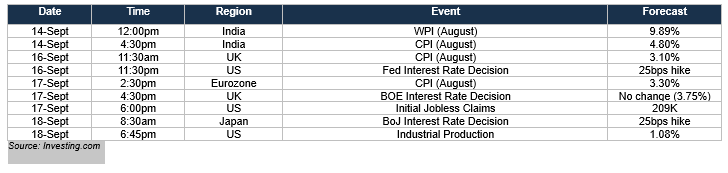
COMING UP THIS WEEK
Disclaimer: The content of this article is for informational purposes only and should not be considered financial or investment advice. Investments in financial markets are subject to market risks, and past performance is not indicative of future results. Readers are strongly advised to consult a licensed financial expert or advisor for tailored advice before making any investment decisions. The data and information presented in this article may not be accurate, comprehensive, or up-to-date. Readers should not rely solely on the content of this article for any current or future financial reference.